
When a commodity multiplies in price, the pain is obvious. The harder problem comes when it falls, because shoppers who absorbed three years of price tags start asking why the chocolate bar in their hand isn’t getting cheaper. Cocoa is now running that experiment in public.
Futures have pulled back sharply from the record highs set during the squeeze, when benchmark contracts traded well above $10,000 a metric ton, a level the market had never seen. The retreat does not erase the damage. Cocoa remains expensive by any historical standard, and the confectioners who spent two years raising prices, trimming bar sizes and rewriting recipes are now caught between costs that have not fully reset and customers who can read a futures chart.
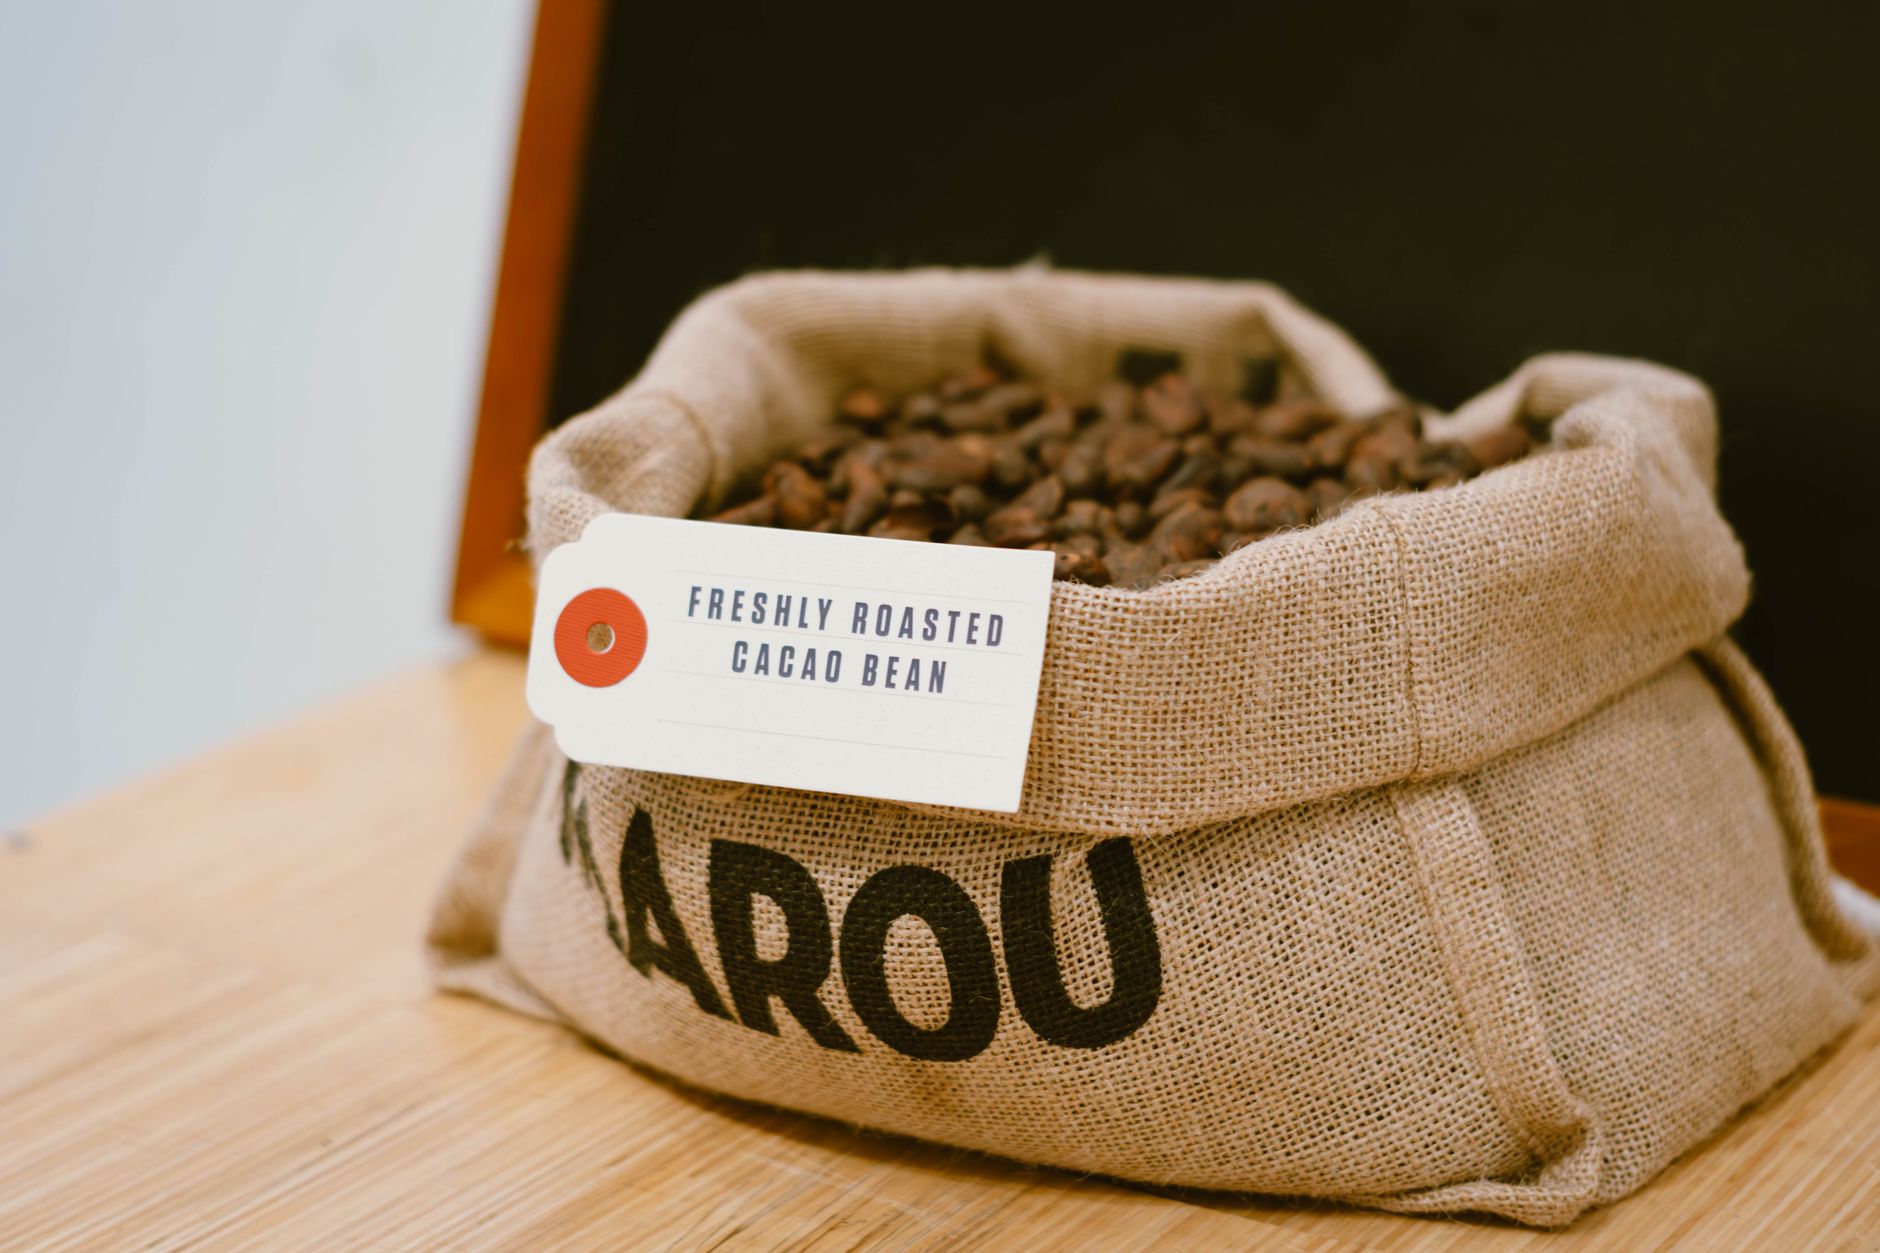
Why the Rally Ran Out of Road
The spike had a physical cause. West Africa grows most of the world’s cocoa, and poor weather, crop disease and aging trees left harvests short for consecutive seasons. A market that was already running thin on stockpiles had no cushion, so every disappointing arrival report pushed prices higher. Records in a thin market tend to feed on themselves, because buyers who fear missing supply bid up contracts further, and that fear inflates the price beyond what the shortage alone would justify.
The cure for high prices is, famously, high prices. Chocolate demand proved less rigid than the industry assumed. Grinding data, which tracks how much cocoa processors turn into butter and powder, weakened as manufacturers cut volumes and consumers traded down or simply bought fewer bars. Once demand falls, the market no longer needs to ration scarce supply as aggressively, and the premium that traders were paying for immediate availability starts to drain away.
Positioning did the rest. Speculative money piled into cocoa on the way up, and a crowded trade reverses quickly once momentum breaks. When prices slip, leveraged holders sell to cut losses, which pushes prices lower, which triggers more selling. Cocoa is a small and illiquid market compared with crude oil or copper, so these moves can overshoot in both directions.
The Hedging Gap Squeezing Margins
Falling futures do not translate into falling costs for chocolate makers, and the reason is mechanical. Large manufacturers buy cocoa months or even years ahead through forward contracts and hedges, so the beans entering their factories today were often priced when the market was near its peak. A manufacturer that locked in supply at elevated levels is now paying above the spot market while its competitors with shorter hedges, or retailers negotiating shelf prices, point to cheaper cocoa.
That gap is where the pressure lands. The company cannot easily cut prices, because its own costs are still high. It also cannot hold them, because buyers have a new argument. A grocery chain negotiating the next contract does not need to understand hedge ratios. It needs only to point at the chart and ask for a discount, and the manufacturer is left defending prices on the strength of a cost base the market has already moved past.
Pricing Power Meets Its Limit
Pricing power in confectionery has always rested on habit. People buy the same bar they bought as children, and brand loyalty allows a manufacturer to pass along cost increases with limited loss of volume. The cocoa surge tested that assumption harder than any event in recent memory, and the results were mixed. Premium brands with strong identities held their ground better, while the middle of the market, where shoppers compare unit prices and promotions, lost volume.
The retreat in cocoa changes the negotiating position of every player in the chain. Retailers gain leverage to demand promotions and to expand private-label ranges, which are built on the premise that a shopper will accept an unfamiliar wrapper for a lower price. Private-label chocolate benefits twice, first from consumers who traded down during the price spike and then from a cost environment that makes their margins workable at a lower shelf price. Branded manufacturers, meanwhile, must decide whether to defend list prices and accept further volume losses or to return to discounting and accept thinner margins.
Reformulation complicates the picture. During the spike, many manufacturers reduced cocoa content, leaned on cheaper fats or fillers, or shrank portion sizes rather than raise sticker prices. Those moves were easier to make than to reverse. Restoring a recipe means giving back savings the company may still need, and shoppers who noticed the smaller bar may not be won back by a price cut that merely returns the product to what it was.
The supply side offers its own warning. Higher prices have encouraged more planting and better farmgate payments in producing countries, but new trees take years to bear fruit, and disease and weather problems have not disappeared. If a lower price discourages farm investment, or if another poor harvest arrives while stockpiles remain lean, the market that just fell could snap back, and chocolate makers who cut prices in the meantime would be exposed again with no hedge and no goodwill from the customers they just discounted for.