
The Tax Credit That Built an Industry Is Now Helping to Break It
The federal Investment Tax Credit kept residential and commercial solar installation booming for nearly two decades. Developers built business models around it, hired aggressively on the assumption it would hold, and priced contracts with the credit baked in as a given. When the ITC step-down schedule began reducing the credit percentage, those assumptions cracked fast – and the companies carrying the most debt and the thinnest margins cracked with them.
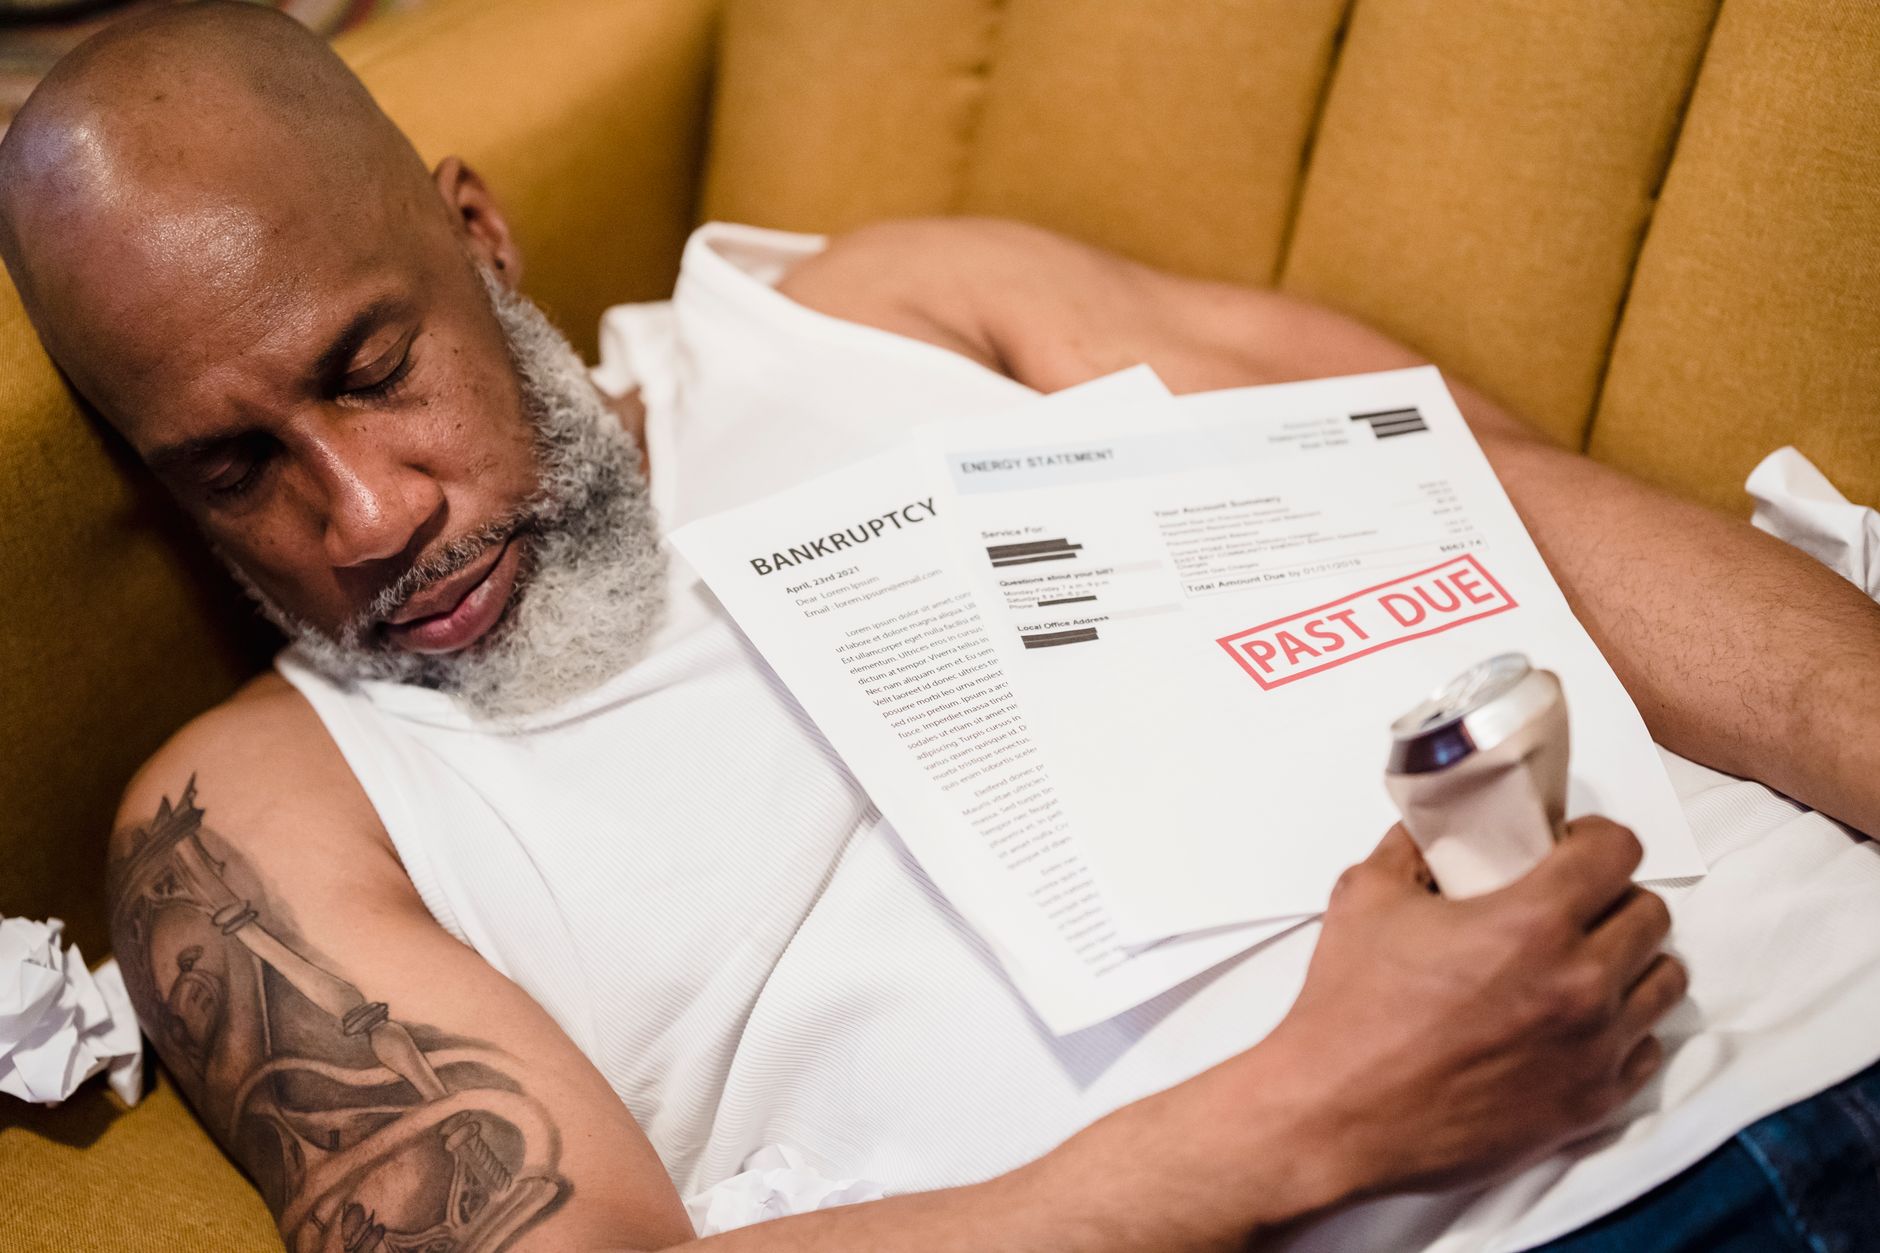
Bankruptcy filings among small and mid-sized solar installers have climbed noticeably over the past 18 months, a pattern concentrated in states where installation volume had surged the fastest. California, Texas, and Florida – markets that drove the residential solar explosion – are now seeing some of the highest concentrations of distressed operators.
The ITC step-down was always written into the law. The industry had years to prepare.
Why the Math Stopped Working
The core problem is a margin squeeze that operates on two sides simultaneously. When the credit was higher, installers could price competitively while still maintaining enough room to cover overhead, financing costs, and the cost of the panels themselves. As the credit stepped down, homeowners and commercial buyers expected prices to remain roughly stable – or even fall, given that panel costs have dropped sharply. Installers absorbed the gap rather than pass it through, because competition made raising prices nearly impossible in saturated markets.
The companies most exposed are those that grew headcount and infrastructure during the boom years by taking on loans or revolving credit lines. A residential solar installer carrying significant payroll and warehouse costs needs consistent volume to stay solvent. When volume slows – as it has in some markets due to rising interest rates making solar financing less attractive to homeowners – the fixed cost base becomes a trap. Revenue drops faster than expenses can be cut, and the cash runway disappears in months, not years.
Larger installers with diversified revenue across commercial, utility-scale, and residential segments have more cushion. The companies failing now are disproportionately those that specialized in residential only, often in a single metro region. That concentration worked as a growth strategy when demand was expanding. It became a liability the moment demand softened and margins tightened at the same time.
The Ripple Effects Hit Customers and Workers
When a solar installer goes bankrupt, the consequences are not just financial headlines. Homeowners who signed contracts and paid deposits are left with unfinished installations, voided warranties, and no obvious recourse. Solar panels installed by a company that no longer exists can also create complications if the homeowner later needs service work or wants to file a warranty claim on the equipment itself – manufacturers’ warranties typically survive the installer’s collapse, but exercising them requires navigating processes most homeowners are not equipped to handle.
Workers face the more immediate impact. Solar installation has been a significant source of skilled trades employment, and the companies shutting down now are concentrated employers in their local markets. A mid-sized installer employing 80 to 150 technicians, project managers, and sales staff represents a meaningful local labor market event when it folds. Reabsorption into surviving competitors is possible in healthy markets, but in areas where multiple installers are struggling simultaneously, that assumption does not hold.
The supplier chain also feels the pressure. Distributors and equipment suppliers who extended trade credit to installers now find themselves as unsecured creditors in bankruptcy proceedings. For smaller distributors without the balance sheet to absorb those losses, a cluster of installer failures in their region can threaten their own solvency. The financial distress is not self-contained.
What Survives and What Doesn’t
The installers positioned to come through this period are those that either moved up-market into commercial and industrial installations – where contract sizes are larger and margin structures differ from residential – or that locked in long-term service and maintenance agreements that provide recurring revenue independent of new installation volume. Recurring revenue does not save a company that is hemorrhaging cash, but it does create a floor that pure installation shops lack entirely.
Consolidation is already happening. Larger regional players and national brands are acquiring distressed competitors at discounts, picking up their customer lists, their crews, and sometimes their equipment. This accelerates a trend toward market concentration that was already visible before the step-down tightened margins. The residential solar market may look substantially different in three years – fewer, larger operators with more pricing power and less of the competitive fragmentation that kept consumer prices low during the boom.
The Inflation Reduction Act extended and in some cases restored ITC levels for certain project types, which has created an uneven landscape where some segments of the market have renewed subsidy support while others do not. Navigating that complexity requires legal and financial infrastructure that small installers generally do not have. The policy environment now functionally advantages scale in ways that pure market competition never did.
For homeowners still weighing a solar installation, the practical question is whether the company they are signing with will still exist when they need warranty service in five years – and right now, that is not a question with a comfortable answer for everyone in the market.
Frequently Asked Questions
Why are solar installers going bankrupt now?
The federal Investment Tax Credit step-down reduced the subsidy that installers relied on to maintain margins, while rising interest rates simultaneously dampened homeowner demand, creating a cash flow crisis for companies with high fixed costs.
What happens to my solar panels if my installer goes bankrupt?
Manufacturer warranties on equipment typically survive an installer’s bankruptcy, but homeowners may face unfinished installations, voided service contracts, and complicated warranty claim processes with no installer to assist them.