
When the Local Bank Disappears
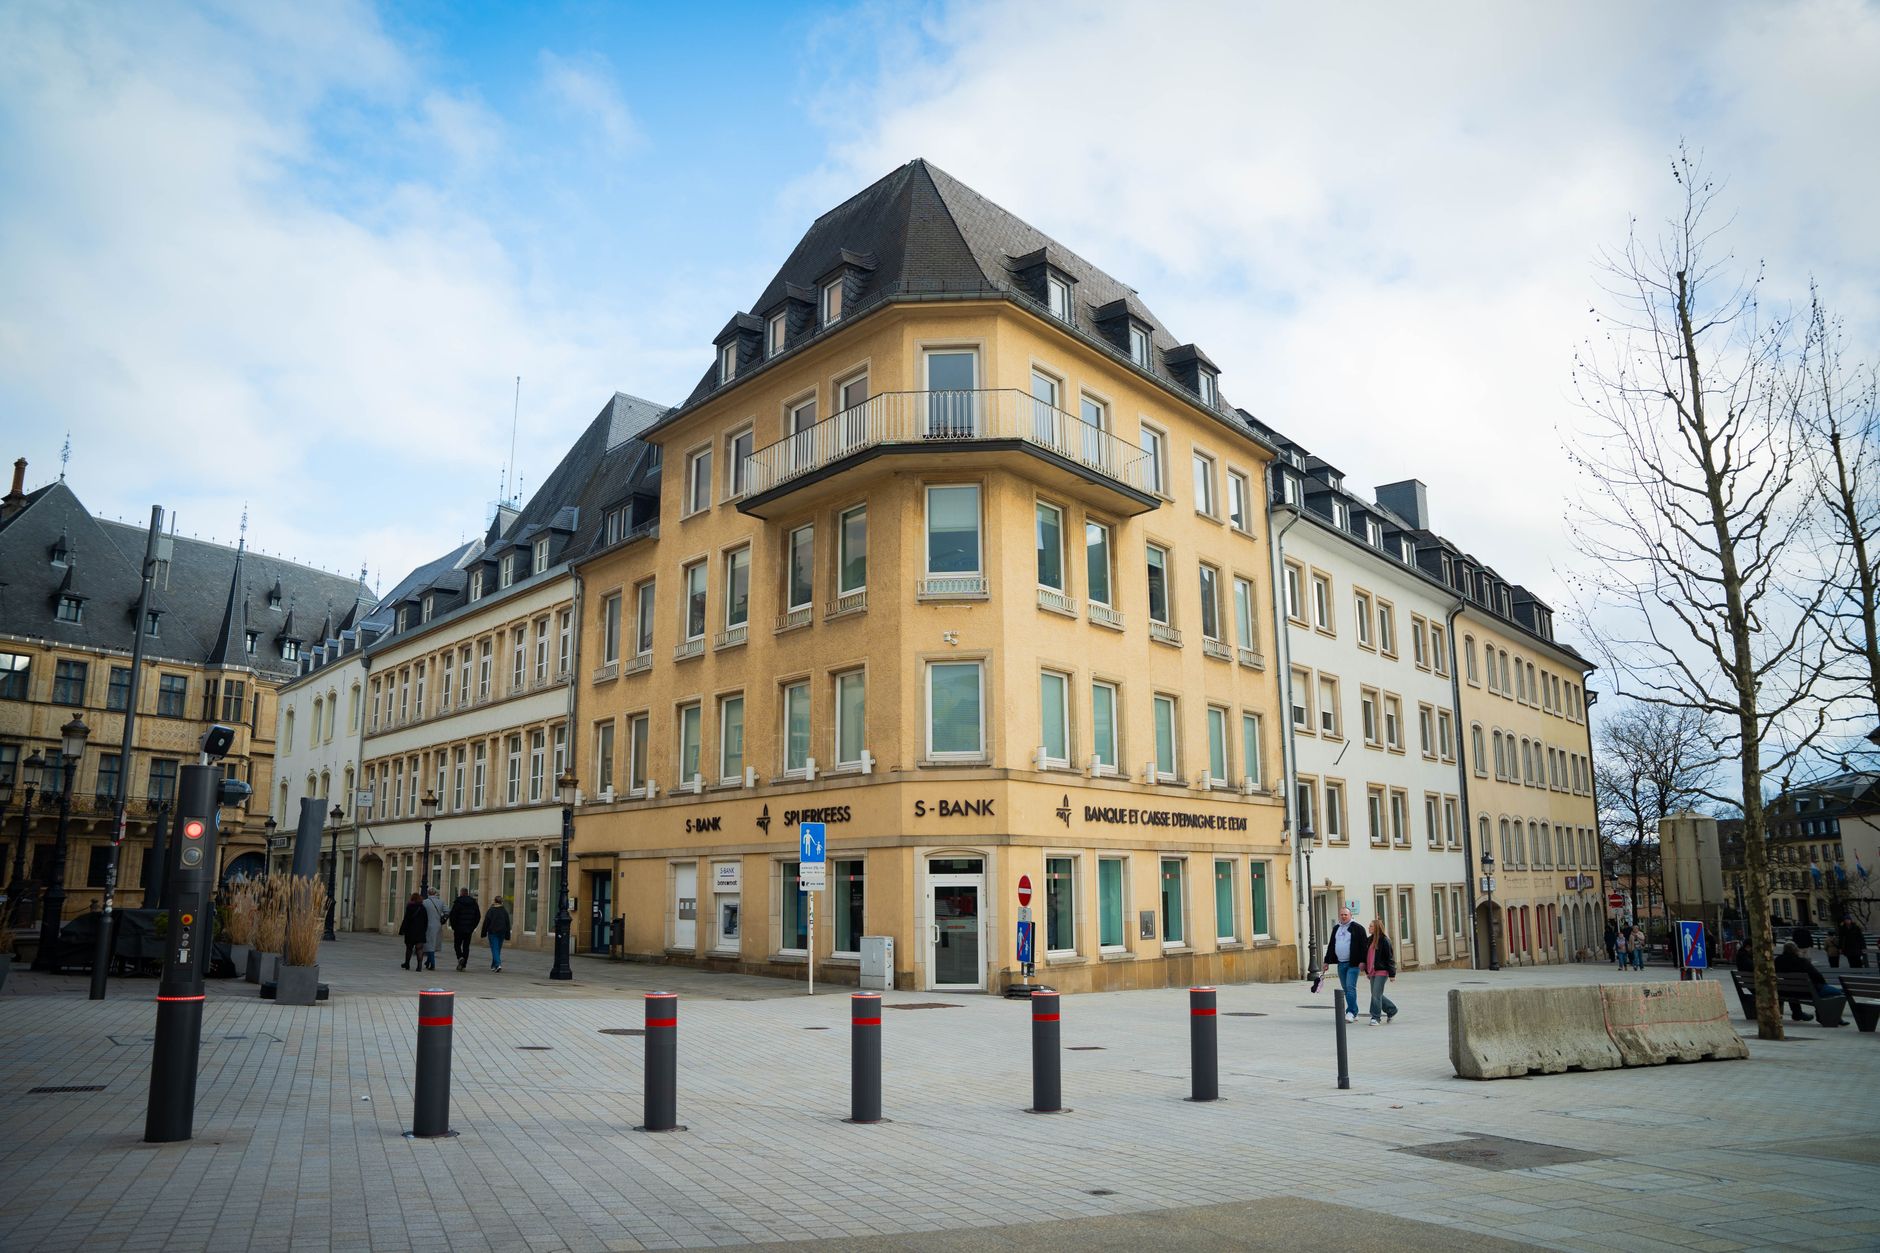
Community banks have long been the primary credit source for small businesses that lack the financial profile to attract attention from large national lenders. A Main Street bakery, a regional trucking company, a family-owned hardware store – these are borrowers that community banks understood because their loan officers lived in the same zip codes, knew the owners personally, and could weigh character and local market knowledge alongside a balance sheet. That relationship-based lending model is now under serious pressure as community bank mergers accelerate across the country, consolidating institutions that once competed for small business customers into larger regional banks with different lending priorities.
The pace of consolidation has been building for years, but the current interest rate environment has pushed more community banks toward merger negotiations. Higher borrowing costs have squeezed net interest margins at smaller institutions, which lack the diversified revenue streams that help large banks absorb rate cycle pressure. For small business owners, the practical consequence is that the banker who approved their last loan may no longer work at an institution that makes the same kinds of loans at all.
What Consolidation Actually Does to Credit Access
When a community bank is absorbed into a larger institution, the acquiring bank typically imposes its own underwriting standards, credit scoring models, and loan size minimums. Those standards are usually designed for scale – built to process high volumes of applications efficiently, not to evaluate the nuanced creditworthiness of a borrower whose financials look messy on paper but whose business is genuinely healthy. A small landscaping company with seasonal revenue swings, for instance, may score poorly under an automated underwriting system even if a local loan officer would have recognized immediately that the pattern was normal for that type of business in that region.
Loan size thresholds become a particular problem after mergers. Larger banks often find small business loans under a certain dollar amount – sometimes $250,000, sometimes less – unprofitable to originate given their overhead and compliance costs. So those loan products quietly disappear from the menu, or the application process becomes so burdensome that small business owners give up before completing it. The businesses that most need credit access are frequently the ones applying for the smallest amounts.
The Ripple Effects on Small Business Financing
Small businesses turned away from traditional bank credit don’t simply stop needing capital. They look elsewhere, and the alternatives are almost always more expensive. Online lenders and fintech platforms have expanded into the gap left by retreating community banks, offering faster approvals but charging interest rates that can run significantly higher than what a community bank would have offered. For a business operating on thin margins, the difference between a 7% bank loan and a 24% fintech line of credit can determine whether an expansion is viable or not.
The Small Business Administration’s loan programs exist partly to address this kind of credit gap, but SBA loans come with their own friction. The application process is extensive, approval timelines can stretch for months, and many smaller lenders that once originated SBA loans have exited the program as compliance costs rose. A business owner who needs $80,000 to replace a piece of equipment before a key contract starts cannot always wait three months for a government-backed loan to close.
Credit unions have picked up some of the slack in certain markets, and some states have launched small business lending programs through their economic development agencies. But neither channel has the geographic reach or lending capacity to fill the hole left by hundreds of community bank mergers. The math simply does not add up – the number of institutions capable of doing small-dollar, relationship-based business lending has been shrinking faster than alternatives can grow.
Owners who have been through a bank merger often describe the same experience: a letter arrives announcing the acquisition, followed by a transition period where everything seems normal, followed by a gradual realization that the new institution is not particularly interested in renewing their credit line on the same terms. By the time they recognize the problem, they may have months, not years, to find a new banking relationship. Small businesses carrying variable-rate debt are also navigating this credit access squeeze at the same time they are managing higher borrowing costs – a pressure that has contributed to rising default rates in segments like vehicle-secured commercial debt, where negative equity has become a compounding problem for businesses relying on fleet financing.
The Geography of the Problem
Credit tightening from bank consolidation is not distributed evenly. Rural markets and smaller cities are disproportionately affected because community banks often hold a larger share of local lending activity in those areas. When a rural county loses its only locally headquartered bank to a merger, the replacement institution may be a regional bank headquartered three states away with no particular incentive to prioritize that county’s small business lending needs. The relationship infrastructure that made credit work in that market simply does not transfer to the acquiring bank’s balance sheet.
Urban and suburban markets are not immune, but they typically have more lender diversity to absorb the shock. A small business owner in a major metro area who loses their community bank relationship has more options to pursue than someone operating in a county seat with a population of 8,000.
Where This Leaves Small Business Owners
The practical advice that circulates among small business owners is to build banking relationships before they are needed, not during a crisis. Maintaining accounts at multiple institutions, keeping a community bank relationship active even during periods when credit is not needed, and documenting business financials in formats that align with what underwriters want to see – these are the defensive moves that create options when credit markets tighten. A business with an established three-year relationship with a community bank is in a different position than one applying cold for the first time when cash flow is already stressed.
Credit unions with small business charters have become more relevant as community bank density has declined. Some have expanded their commercial lending programs aggressively, and their member-ownership structure creates a different incentive than shareholder-driven commercial banking. They are not a universal solution – many credit unions still have strict member eligibility requirements and limited commercial lending expertise – but they represent a genuine alternative worth evaluating before a financing need becomes urgent.
The structural problem, though, is not one that individual business owners can fully navigate around. When the lending infrastructure in a region consolidates down to a handful of large institutions, the options contract regardless of how well-prepared any individual borrower is. Regulators have the authority to condition bank merger approvals on community reinvestment commitments, and the Community Reinvestment Act theoretically requires banks to serve the credit needs of the communities where they operate – but enforcement has historically been uneven, and CRA assessments have rarely blocked mergers that were otherwise approved. With another wave of community bank consolidation already in motion, the question facing small business owners is not whether credit access will tighten further, but how much.
Frequently Asked Questions
Why do bank mergers reduce small business lending?
Acquiring banks typically apply stricter underwriting models and higher minimum loan sizes that exclude many small business borrowers who qualified under the original community bank’s relationship-based standards.
What alternatives do small businesses have when community banks merge?
Options include online lenders, credit unions with commercial charters, SBA loan programs, and state economic development lending – though each comes with higher costs, slower timelines, or eligibility limitations.