
A New Market Hiding in Plain Sight
The Inflation Reduction Act did something few tax bills manage to do: it created an entirely new financial product. When Congress authorized the transfer of clean energy tax credits to unrelated third parties in 2022, it opened a mechanism that had never existed before – companies generating renewable energy credits could now sell them directly to corporations hungry for tax relief. The sellers get immediate cash. The buyers get a dollar-for-dollar reduction in their federal tax bill, typically at a discount to face value. The logic is clean, the math works, and the market has been filling in around it fast.
What nobody fully anticipated was how quickly a specialized brokerage layer would form to sit between those two sides.
Brokers in this space operate as matchmakers between renewable energy developers – solar farms, wind projects, battery storage installations – and corporate tax buyers that range from regional banks to Fortune 500 manufacturers. The credits typically trade somewhere between 88 and 95 cents on the dollar, depending on credit type, seller risk profile, and deal structure. The spread sounds thin, but at transaction sizes that routinely run into eight figures, thin spreads generate serious revenue. Several firms that were handling traditional tax equity deals just two years ago have now repositioned almost entirely around credit transfers, hiring legal and due diligence staff specifically for this product.
Who Is Buying and Why
The buyer profile in this market is not what you might expect. Early assumption was that large financial institutions would dominate the buyer side – and they are present – but the more active buyers tend to be mid-size corporations with consistent tax liabilities and treasury teams sophisticated enough to execute the paperwork without outside counsel on every deal. A manufacturing company sitting on a $20 million annual federal tax bill can purchase $20 million in credits for something closer to $18.5 million, effectively cutting its tax cost by roughly 7.5 percent. That is a guaranteed, risk-adjusted return that no money market fund or short-duration bond is going to match right now.
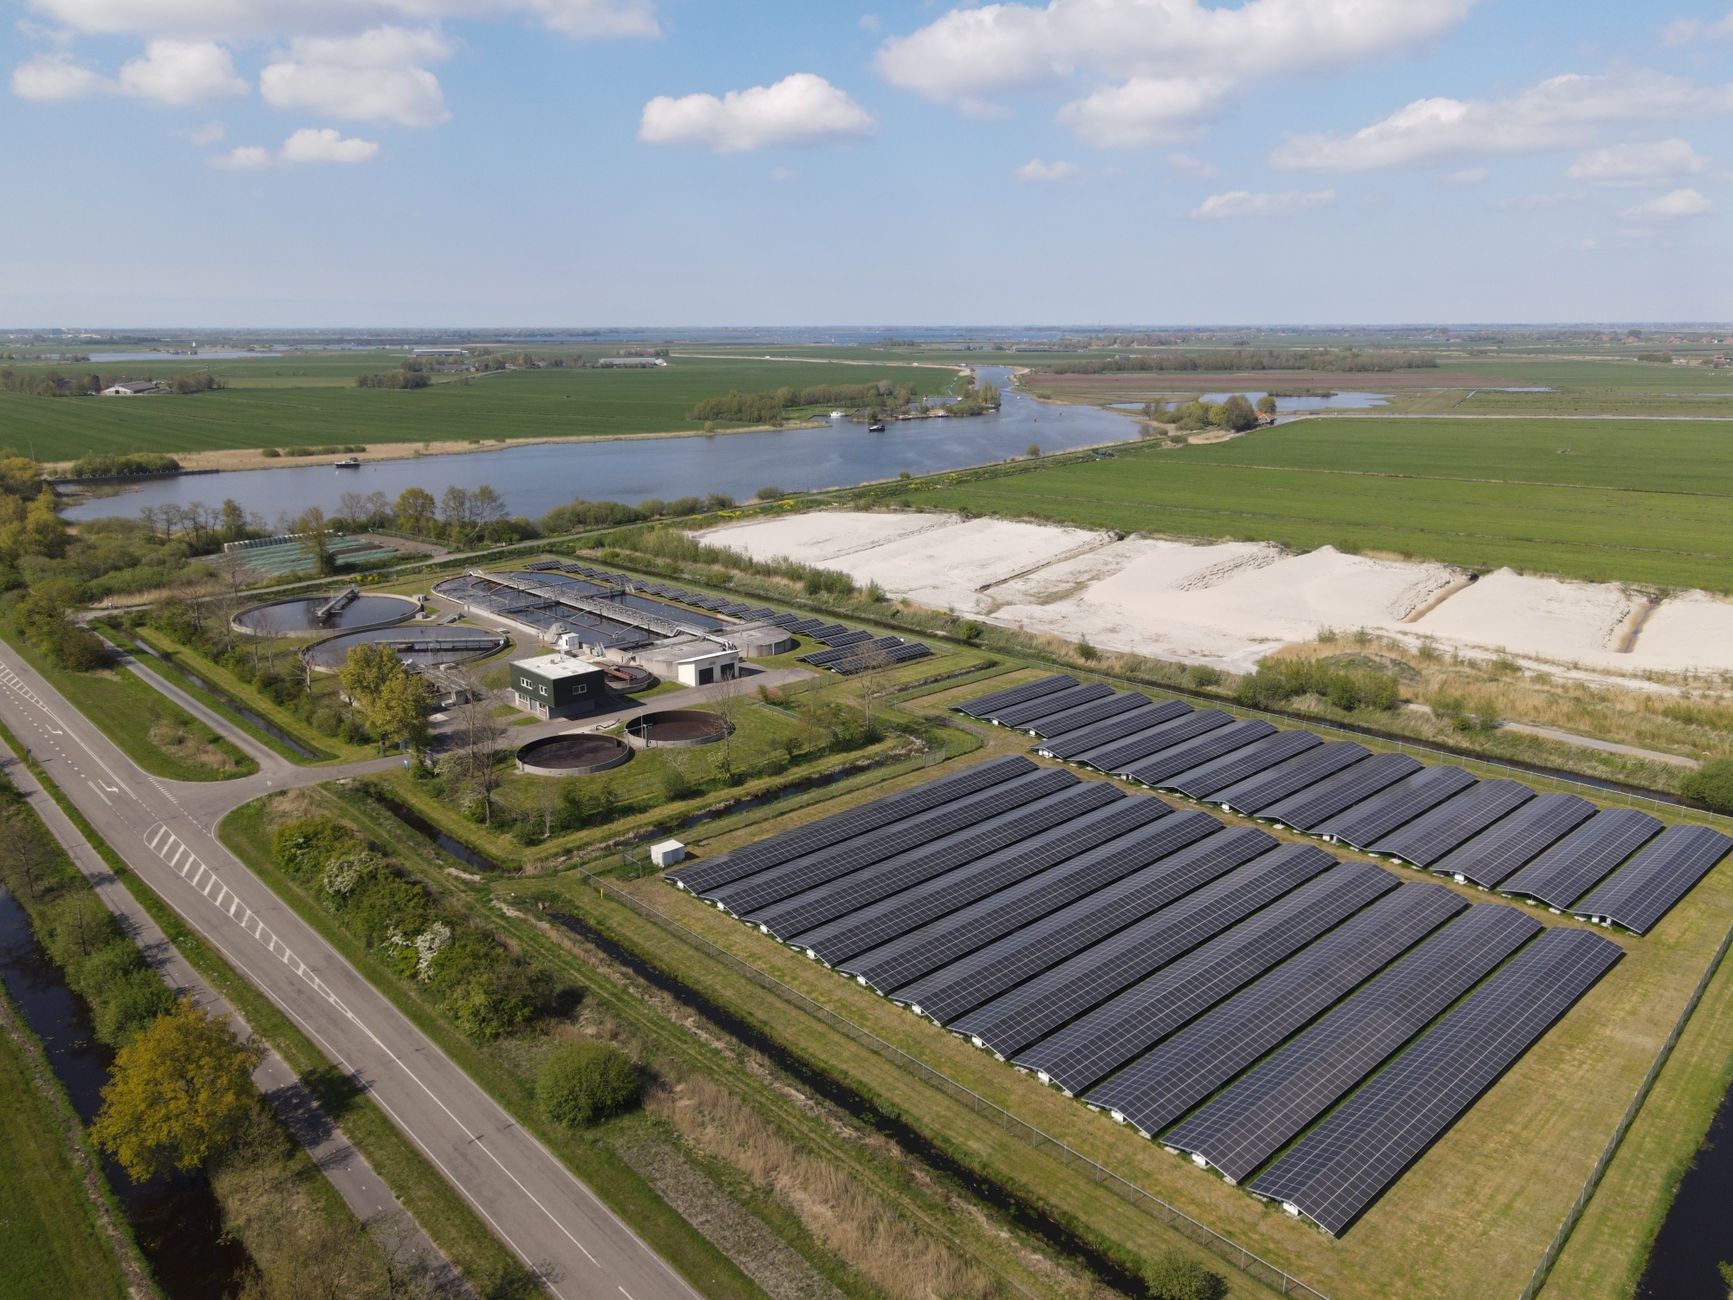
The seller side skews toward developers who need to recycle capital quickly. A solar developer that has built and commissioned a project has credits sitting on the books but may not have the tax appetite to use them internally, particularly if the project was structured with outside equity that already absorbed the depreciation benefits. Selling the credits provides liquidity without diluting ownership or taking on additional debt. For smaller developers operating in the five to fifty megawatt range, this mechanism has effectively replaced certain financing structures that were too administratively complex to access before 2022.
Transferability has also changed the negotiating dynamics within project finance. Developers now enter construction with a cleaner picture of what their credit monetization will look like because the transfer market gives them a committed exit that tax equity never quite guaranteed. That pricing visibility flows back into how lenders underwrite construction loans, how sponsors model returns, and ultimately how aggressively developers bid on new projects.
The Brokerage Build-Out
The firms building around this market are not traditional investment banks, and they are not insurance brokers rerouted into a new product line. Most are purpose-built shops, or restructured practices within existing advisory firms, staffed by people who came from tax equity, structured finance, or energy project development. The skillset required is narrow: you need to understand how the credits are generated and certified, how representations and warranties function in a transfer agreement, what triggers a recapture event under IRS rules, and how to get corporate tax departments comfortable enough to actually close. That last point is where deals fall apart most often. A corporate buyer with no prior experience in energy finance can spend three months in diligence before walking away because their tax counsel gets cold feet.
To address that friction, several brokers have started offering standardized transaction documents and pre-negotiated representations frameworks that compress the diligence timeline. Some have partnered with insurance carriers that write tax credit insurance – policies that protect buyers against IRS recapture risk. That insurance layer has done more to accelerate buyer adoption than any amount of market education, because it converts an unfamiliar risk into a known premium cost that a CFO can approve in a single meeting.
The fee structures brokers charge vary, but most work on a basis-point spread embedded in the transaction rather than an explicit advisory fee. That makes the cost invisible to buyers who are focused on the net credit price and attractive to sellers who are comparing this channel against the alternative of building out an in-house sales function. The model works until the market gets crowded enough that spread compression forces consolidation – a dynamic that is already beginning to show up in conversations across the sector.
Where the Pressure Points Are
The IRS has not issued comprehensive guidance on every edge case in the transferability rules, and that ambiguity is the single largest overhang on the market. Certain credit types – particularly those with adder bonuses tied to domestic content or energy community location requirements – carry higher recapture risk if the underlying project fails to meet certification standards at audit. Buyers with aggressive tax positions and limited appetite for controversy are pricing that risk into the discount they demand, which compresses proceeds for sellers of those specific credit categories. Until the agency clarifies its audit posture on a broader set of scenarios, the market will continue pricing in uncertainty that may or may not be warranted – and the brokers sitting in the middle will keep earning fees for navigating exactly that ambiguity.
Frequently Asked Questions
What is a renewable energy tax credit transfer?
It allows companies that generate clean energy tax credits to sell them to unrelated third parties, who use them to offset their own federal tax liability, typically at a discount to face value.
Who buys transferred tax credits and why?
Mid-size and large corporations with consistent federal tax bills buy transferred credits because purchasing them at a discount – often 88 to 95 cents on the dollar – reduces their effective tax cost more reliably than most short-term investments.
What risks do buyers face in the tax credit transfer market?
The primary risk is IRS recapture, which can occur if the underlying energy project fails to meet certification or compliance standards. Many buyers now purchase tax credit insurance to cover this exposure.