
When the Policy Disappears, the Deal Dies
Flood insurance nonrenewal notices have become a quiet deal-killer in coastal real estate markets, arriving in mailboxes with little warning and leaving sellers stranded mid-transaction. In states like Florida, Louisiana, and South Carolina, a growing number of homeowners are discovering that their flood coverage – long treated as background paperwork – has been dropped by private insurers or scaled back by the National Flood Insurance Program, effectively making their properties unsellable to buyers who need a mortgage.
The mechanics are straightforward and brutal. Most mortgage lenders require active flood insurance as a condition of financing. No policy, no loan. And with private carriers pulling back from high-risk coastal ZIP codes and NFIP premiums rising sharply under the agency’s Risk Rating 2.0 overhaul, sellers are watching closings collapse not because buyers walked away, but because no insurer will write the coverage needed to make the deal legal.
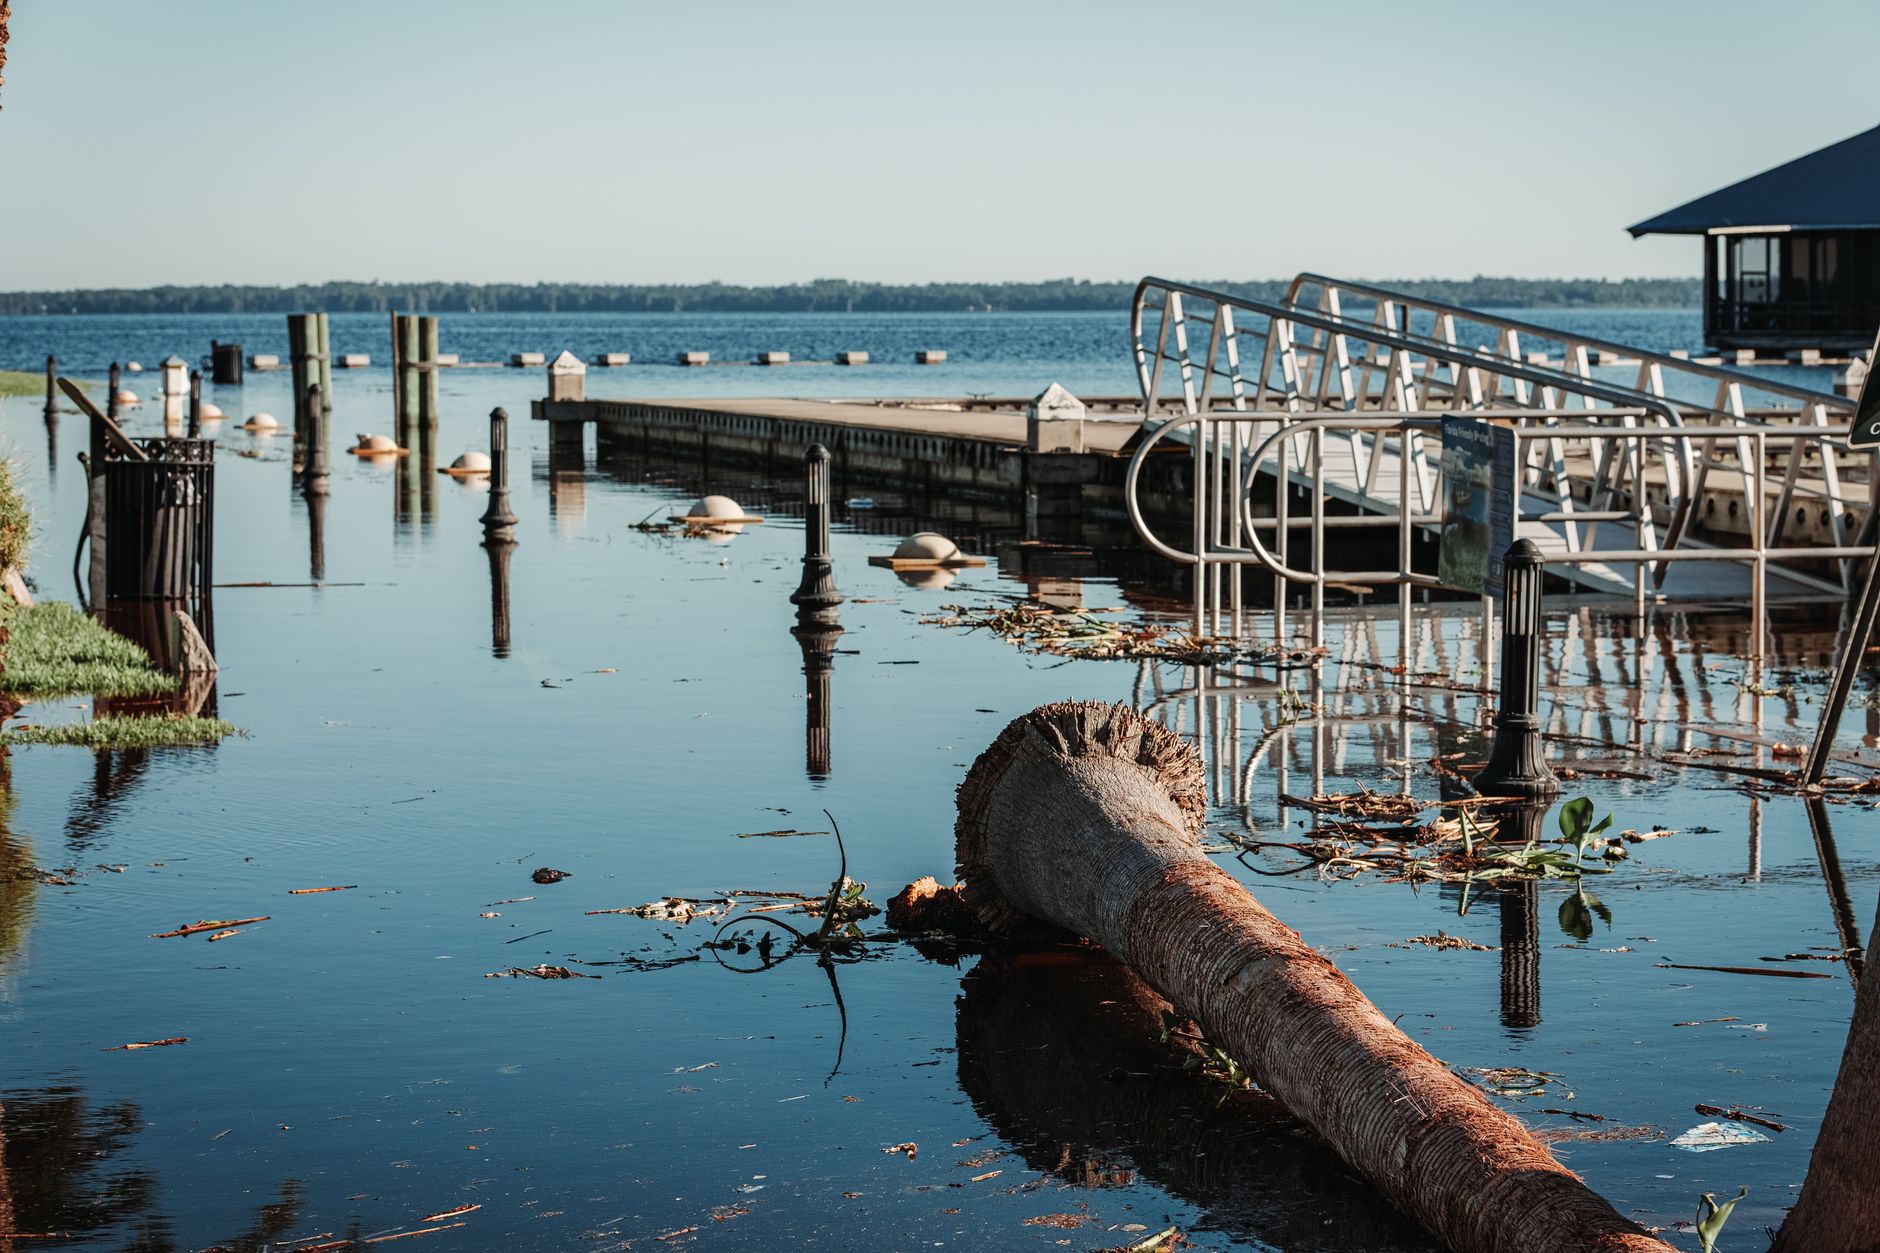
How the Insurance Retreat Is Reshaping Coastal Markets
Private flood insurers have been quietly exiting coastal markets for several years, but the pace accelerated after a string of costly hurricane seasons strained carrier balance sheets. Companies operating in Florida’s coastal counties, in particular, began nonrenewing policies en masse, citing actuarial losses that made continued coverage financially indefensible. Some carriers left the state entirely rather than absorb another season of claims.
The NFIP, which was designed as the insurer of last resort for flood-prone properties, absorbed much of the overflow – but the program’s Risk Rating 2.0 system, fully implemented in 2022, repriced policies to reflect actual property-level flood risk rather than community-wide averages. For many coastal homeowners who had paid modest premiums for decades, the repricing produced rate increases that doubled or tripled their annual costs. Some chose not to renew rather than absorb the shock. Others simply couldn’t afford to.
The result is a growing inventory of coastal homes that are technically available but practically unmortgageable. Sellers who assumed their equity was intact are finding that without insurable coverage, the buyer pool shrinks to cash purchasers only – a far smaller and more price-sensitive group willing to discount heavily for the coverage risk they’re absorbing.
The Transaction Layer Nobody Talks About
Real estate agents working coastal markets describe a new kind of deal delay: the insurance gap. A buyer submits an offer, the seller accepts, and then the insurance search begins. When no carrier will write a policy at a price the buyer can absorb – or at any price – the mortgage application stalls. Unlike a failed inspection or a title dispute, this problem has no obvious fix. You can’t negotiate with a carrier that has decided a ZIP code is simply too risky to insure.
Cash buyers fill some of the void, but they do so on their terms. A property that might have sold at full market value to a financed buyer is instead priced at a discount that reflects both the coverage uncertainty and the limited competition. That discount can be substantial – 10 to 20 percent in some markets – and it tends to compress values across an entire neighborhood, not just for individual sales.
The Compounding Effect on Property Values and Local Tax Bases
When insurance availability disappears from a neighborhood, the effects compound quickly. Falling sale prices reduce the comparable sales data that appraisers use to value neighboring properties, which then affects property tax assessments over the following assessment cycle. Municipalities that depend heavily on coastal property tax revenue – and many in Florida, North Carolina, and Texas do – face a slow erosion of their tax base that mirrors the insurance retreat almost exactly.
Homeowners who aren’t selling face a separate version of the same problem. Without flood coverage, they’re exposed to catastrophic out-of-pocket losses in the event of a storm. Many choose to self-insure quietly, carrying no flood policy and hoping their elevation or their luck holds. That gamble works until it doesn’t, and when a major storm hits an underinsured coastal community, the financial fallout extends far beyond individual households – local governments absorb uninsured infrastructure damage, federal disaster aid gets stretched, and neighborhood recovery drags out for years.
The downstream effect on small coastal businesses and services is equally underappreciated. A neighborhood where homes can’t be sold, can’t be insured, and can’t recover quickly from storm damage is a neighborhood that gradually loses economic activity. Signs of Main Street recession pressure tend to show up in coastal communities losing insurance access faster than in places where the financial stress is more visible.
There’s a policy tension at the center of this problem that hasn’t been cleanly resolved. Risk Rating 2.0 was designed to make flood insurance pricing honest – to stop subsidizing high-risk properties at the expense of lower-risk policyholders. That logic is sound. But honest pricing, applied to markets where private alternatives have already withdrawn, can produce a situation where accurate risk assessment and functional housing markets are working against each other. A home that floods every fifteen years is a real risk. It’s also someone’s primary asset, their retirement equity, and in many cases a multigenerational family property. When the actuarially correct premium is also the unaffordable premium, the policy question of what to do next remains genuinely open.
Frequently Asked Questions
Why are flood insurance policies being nonrenewed in coastal areas?
Private carriers are exiting high-risk coastal markets due to sustained actuarial losses from storm claims, while NFIP’s Risk Rating 2.0 overhaul has sharply raised premiums, prompting some homeowners not to renew.
How does a flood insurance nonrenewal affect a home sale?
Most mortgage lenders require active flood insurance to approve financing. Without a policy, buyers relying on loans cannot close, effectively limiting sellers to cash buyers who typically offer lower prices.